Sunk cost fallacy
A sunk cost is an unrecoverable past expenditure. Decision theory says only incremental costs and benefits, including opportunity costs, should enter the next choice; the sunk cost effect is the finding that the larger the prior investment, the more likely you are to continue.
Arkes and Blumer (1985) named the mechanism the desire not to appear wasteful. Stopping converts a prior spend into an admitted waste, which is aversive; continuing keeps the earlier decision looking sensible. The management literature calls the same thing self-justification, after Staw, and the lab version is not merely a tolerance for a worse bet: in the same paper's Experiment 4, respondents who had already sunk $10 million into a project rated its chance of financial success at 41.0 out of 100 (n = 76), against 34.0 among respondents shown the identical project with nothing spent (n = 82), t(156) = 2.02, p < .05. People who have paid revise the forecast, not just the decision.
Two things sit next to the mechanism and are routinely mistaken for it. The first is the endowment effect — once something is yours you value it more. Ronayne, Sgroi and Tuckwell (2021) separated the two inside one 528-subject design: 23% of the 268 subjects who earned a lottery through a real-effort task (counting letters in blocks of Latin text) declined to switch to a strictly dominant one paying $10 on a 20% rather than a 10% chance, against 7% of the 197 who were simply handed the inferior lottery, and none of the 25 offered the two as a straight choice. The difference in proportions was 0.16, p < .001, which leaves the endowment effect accounting for approximately only a third of the overall effect. The second confusable is proximity to completion, which the escalation literature calls goal substitution: as a project nears its end, finishing becomes a goal in its own right, an argument Sleesman and colleagues trace to Conlon and Garland (1993). This one matters enormously for product work, because the meta-analytic record suggests completion proximity is doing much of the work usually credited to sunk cost.
For an interface this distinction is the whole job. There is a defensible pattern — reflecting value a user genuinely accumulated, so they can see what they have and decide well — and there is the fallacy, which is a reasoning error you would be exploiting rather than serving. The first is closer to endowed progress and the goal gradient effect; where the user built a specific artifact the IKEA effect governs, and where the question is liking rather than continuing, effort justification does. The second is the thing cancellation flows do when they recite how much you have spent. Nothing in the literature licenses inflating switching costs; the evidence is that people already overweight their own past spend without your help.
The baseline field demonstration is old, direct and small. Arkes and Blumer sold season tickets to the Ohio University Theater's 1982–1983 season at the normal $15, a $2 discount or a $7 discount, the ticket types randomly ordered beforehand and the discount revealed only after the buyer had announced an intention to buy; six people buying as couples were dropped, leaving 18, 19 and 17 subjects. Across the first five plays the no-discount group used significantly more tickets (4.11) than the $2 group (3.32) or the $7 group (3.29), one-tailed t = 1.79 and 1.83, p < .05. Read the second half of the season before you quote this as a retention lever: use was 2.28, 1.54 and 2.18 and the groups did not differ. The only significant source of variance in the full analysis was season half, F(1, 51) = 32.32, p < .001 — 3.57 tickets per subject over the first five plays against 2.09 over the last five. The authors' own summary is that the effect lasted for six months following the purchase and was not manifested six to nine months after it.
The scenario evidence is far larger, which should make you suspicious of scenario evidence rather than confident about the effect. In Experiment 3, 41 of 48 respondents (85%) endorsed spending the last 10% of a research budget to finish a radar-blank plane that a competitor had already beaten to market, while only 10 of 60 (17%) endorsed starting the same project from scratch for the same remaining million: chi-square(1, N = 108) = 50.6, p < .001. Experiment 5 removed the obvious confound by pricing the from-scratch plane at the same $10 million and got identical answers, 10 yes against 50 no. The weaker items in the same paper deserve equal billing. In the much-quoted ski-trip question only 46% chose the trip they expected to enjoy more (99% CI 30 to 62%), and the result reproduced when both trips were won in a radio competition rather than bought: 44 of 86 still took the $100 trip, a comparison that did not approach significance. An item that behaves the same way when nothing was sunk is not measuring only what its reputation says. Experiment 10 is the null worth keeping: across 181 students, 61 of them handed the questionnaire by their own economics professor in a class that had covered sunk costs that semester, the chi-square did not approach significance. Knowing about the bias does not switch it off.
The meta-analysis is where the honest story is. Sleesman, Conlon, McNamara and Miles (2012) screened an initial list of 917 articles for determinants of escalation of commitment. Sunk costs had a significant main effect: k = 34, n = 5,524, mean observed r = .195, corrected rho = .243, 95% CI .114 to .373. Two neighbours beat it. Time investment reached rho = .432 (k = 7, n = 1,664, CI .247 to .617), and proximity to project completion rho = .393 on a wider base with a tighter interval (k = 14, n = 3,073, CI .308 to .478). Then the moderator analysis took most of the sunk cost effect back. Where studies explicitly covaried sunk cost with project completion information — the classic nine-of-ten-million-spent, ninety-percent-complete vignette — rho was .528 (k = 5, n = 945, CI .332 to .725); where sunk cost was varied without that covariation, rho was .100 (k = 28, n = 3,821) and the 95% confidence interval ran from −.036 to .236. The authors' own conclusion is that the sunk cost effect may not be as robust as the literature would suggest, and that studies kept attributing to sunk cost what was partly or wholly a completion effect even though the completion argument had been in the literature for over fifteen years. Personal responsibility for the initial decision, from the same table, has the largest evidence base of any determinant they coded: k = 54, n = 8,625, rho = .258, CI .216 to .301.
Field evidence outside the lab exists for consumption, not for software retention. Ho, Png and Reza (2018) used Singapore's certificate-of-entitlement system, which moves the sunk cost of a new car independently of its running costs, across 8,264 cars and 45,195 service visits, and estimated the elasticity of driving with respect to sunk costs at 0.048 (s.e. 0.016). Between January 2009 and January 2013 the average policy-related sunk cost rose 116%, from S$11,278 to S$24,316; the elasticity implies that this was associated with 5.6% more driving, 86 kilometres a month against a sample average of 1,545. They describe it as the first field evidence of the sunk cost fallacy in usage of a major durable good, and their model has the excess usage attenuating over time. Note the magnitude: more than doubling an unrecoverable cost moved usage by about a twentieth. Nothing comparable exists for subscription software, where the closest thing to field data is enforcement data — Gibson Dunn's 2026 survey of negative-option actions records a $7.5 million settlement by the California Automatic Renewal Task Force with a meal-delivery service and, in November 2025, a $4.8 million settlement by 34 states with an online clothing retailer over its paid membership programme. Grade the principle mixed on that record: the direction survives controlled tests, the magnitudes are modest, and the headline correlation is confounded with completion information across much of the literature it rests on.
When it holds
- It holds most strongly when the past investment is paired with visible proximity to completion. That pairing multiplies the corrected effect roughly fivefold over sunk cost presented alone (rho .528 against .100), and completion proximity is the better-evidenced determinant in its own right (rho .393, k = 14, n = 3,073, CI .308 to .478, against .243, CI .114 to .373, for sunk costs). If you are tempted to show “you have spent 40 hours here”, the evidence points instead at “you are three steps from done”.
- It is weak or absent when past spend is presented on its own. A sunk cost cue with no completion information has a corrected correlation whose confidence interval crosses zero. Do not plan a funnel on the assumption that reminding someone what they paid will reliably hold them.
- Time investment outperformed money in the meta-analysis (rho .432 against .243), though on only seven effect sizes. Effort and time accumulated inside a product are the plausible lever, which is also why this principle blurs into effort justification and the IKEA effect.
- Responsibility for the original decision carries more evidence than the spend does. Personal responsibility for the initial decision had the largest base of any determinant coded (k = 54, n = 8,625, rho = .258), and in Arkes and Blumer's scenarios the first-person president escalated more than a third-person judge of the same company (85% against 64%, chi-square(1, N = 106) = 5.25, p < .05) — though their second attempt at the same manipulation found nothing, so treat it as a direction rather than a dial. A user who actively chose the plan is a different case from one who was defaulted into it.
- Salient opportunity costs lower escalation overall without blunting the sunk cost link. Opportunity cost information had a negative main effect on escalation (rho −.380, k = 6, n = 692, CI −.598 to −.162), so naming the alternative is worth doing on its own merits. But Sleesman and colleagues' prediction that salience would strengthen the sunk cost relationship went unsupported even at p < .10 (rho .372 with opportunity costs present, k = 8, against .137 without, k = 22). Nothing here shows that showing the alternative defuses a sunk cost.
- Mental accounting may gate it. Sleesman and colleagues point to evidence that people escalate on sunk costs when they have not set a mental-accounting budget or find expenses hard to track, and may de-escalate when they have. Legible spend and usage tracking in your product is not neutral ground for this effect.
- Culture moderates it. Pattaratanakun and Mak (2015) ran four sequential-search experiments and found that participants from a collectivist Eastern culture oversearched when search costs were high, reversing the undersearch bias found in Western samples; a cultural-priming manipulation using the language of the program interface reproduced the difference in bicultural participants, and making sunk costs non-salient largely mitigated it. Two consequences for you: an effect size measured on one market does not transfer, and the interface language itself can flip which pattern you observe.
- Individual differences are real but not actionable at the segment level. A standard deviation more cognitive reflection cut the probability of sunk cost behaviour by about 11 to 12 percentage points and a standard deviation more crystallised intelligence by about 17 to 18, while fluid intelligence and openness predicted nothing (Ronayne et al. 2021); economics education predicted nothing either (Arkes and Blumer 1985). You cannot debias your users by explaining the bias to them.
- The effect decays. The theatre effect was present over the first six months after purchase and absent from six to nine months out. The durable-good model in Ho et al. has the excess usage attenuating over time by construction. Treat any sunk-cost-shaped retention effect as a short window, not a moat.
How to apply
- Preselect and surface completion, not expenditure. If there is a genuine goal — profile set up, project shipped, course finished — show distance to the goal. That is the version of this family with the strongest meta-analytic support, and it is honest about what the user gets.
- Build usage summaries that are decision-grade, not guilt-grade. A summary that shows what someone created, where it lives, and what happens to it on cancellation helps them decide. The same screen phrased as “you have invested 142 hours” is the fallacy with a progress bar.
- Make collections and personal libraries concretely useful: searchable, exportable, portable. Accumulated value that a user can take with them is real value. Accumulated value that only exists while they pay is a switching cost dressed as a benefit.
- Use a year-in-review or period recap as a value report, and put the export and the downgrade options in it. If the recap can only be read as an argument against leaving, it is doing the wrong job.
- Where a user is mid-task, say what is unfinished and what finishing requires — the Zeigarnik effect and the goal gradient working on an actual open loop rather than on remorse about past payment.
- On a cancellation screen, state what is irreversibly lost, what is retained, what can be exported, and when the access ends. Facts about the future are legitimate; recitations of the past are not.
- If you measure a sunk-cost-shaped effect in your own funnel, check whether you have confounded past spend with proximity to completion. The meta-analytic literature made exactly that mistake for over fifteen years.
What to avoid
- Cancel flows that recount past spend, tenure or accumulated effort in order to shame the user into staying. This is the anti-pattern, and it is also the pattern regulators collect complaints about.
- Manufactured investment. Busywork, forced configuration or progress that does not correspond to anything the user can use is an attempt to create a sunk cost rather than reflect one. It raises switching cost without raising value, and it is the line that separates the IKEA effect from a dark pattern.
- Burying the exit. ROSCA, 15 U.S.C. § 8403, makes it unlawful to charge for a negative-option online transaction unless the seller clearly and conspicuously discloses all material terms of the transaction, obtains the consumer's express informed consent before charging, and provides simple mechanisms for a consumer to stop recurring charges. That statute is in force regardless of rule status.
- Assuming click-to-cancel is dead. The FTC's Negative Option Rule was finalised on 16 October 2024 and published in the Federal Register on 15 November 2024; the Eighth Circuit vacated it in its entirety in July 2025 on Magnuson-Moss procedural grounds, principally the absence of a preliminary regulatory analysis that a later analysis could not cure. On 12 February 2026 the FTC took final action recodifying the Negative Option Rule as it stood before the 2024 amendments, and on 13 March 2026 it published an advance notice of proposed rulemaking under docket FTC-2026-0265, comments due 13 April 2026. Vacatur removed a rule, not the enforcement theory: ROSCA and Section 5 of the FTC Act remain, and states including California, Colorado, Minnesota and New York have strengthened their own disclosure, reminder and cancellation requirements.
- Letting a retention flow eat into a withdrawal right. Under Article 9(1) of Directive 2011/83/EU, and save where the Article 16 exceptions apply, a consumer has a period of 14 days to withdraw from a distance or off-premises contract without giving any reason; for service contracts Article 9(2) runs that period from the day the contract is concluded. A friction-laden cancel path that pushes a user past day 14 is not a clever retention mechanic.
- Framing a refund or a price already paid as a reason to continue. That is the fallacy stated outright, and in a paid context it edges toward a misleading omission rather than a nudge.
Real-world examples
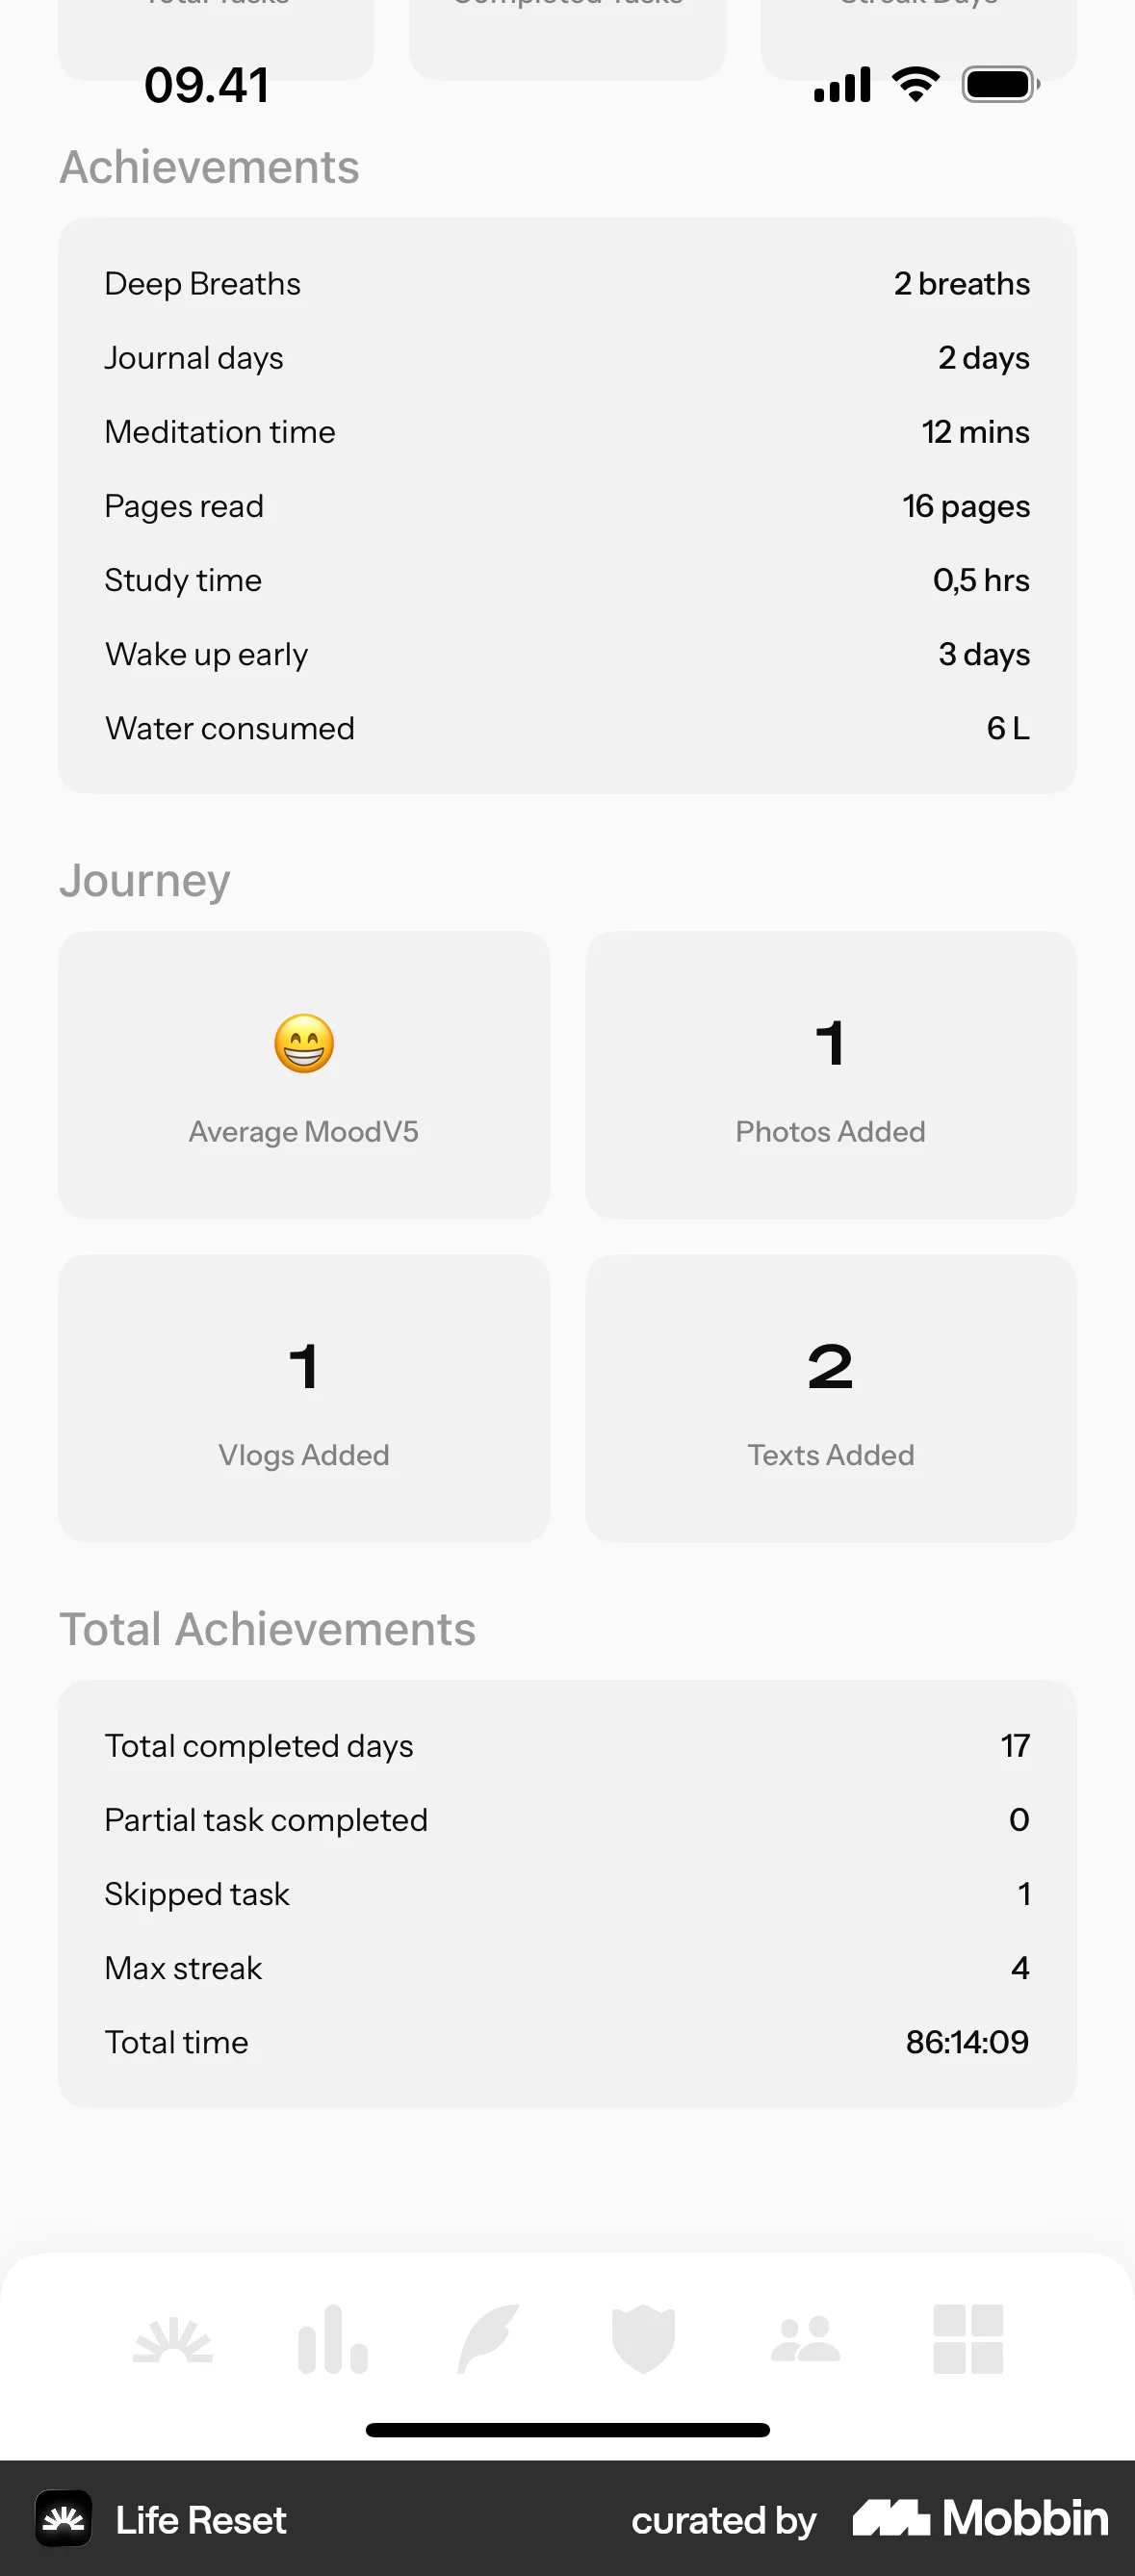
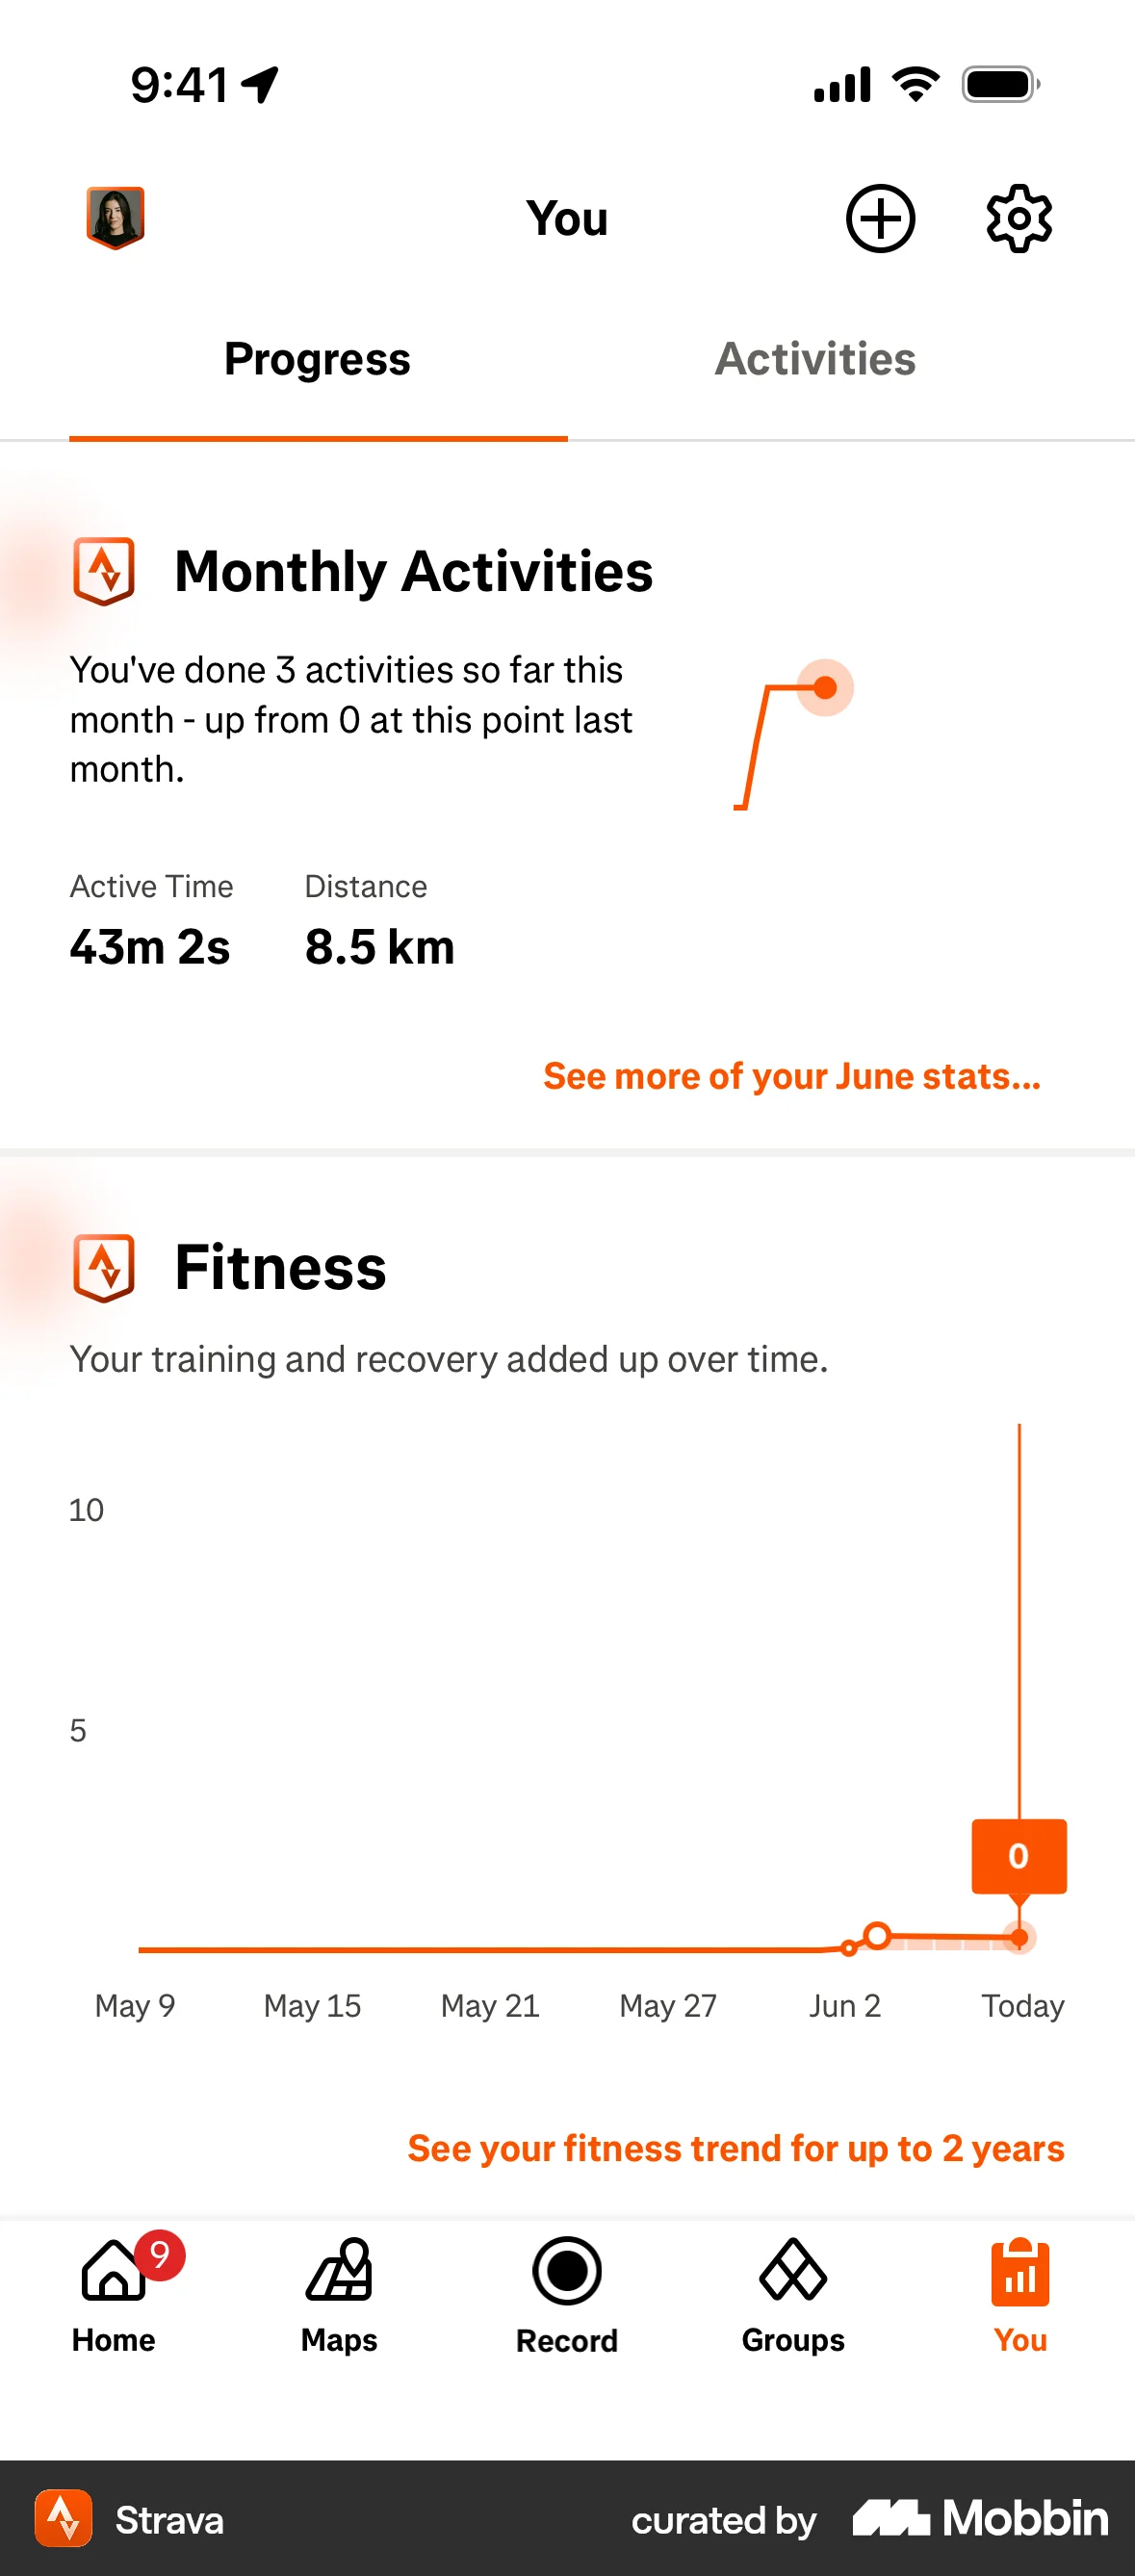
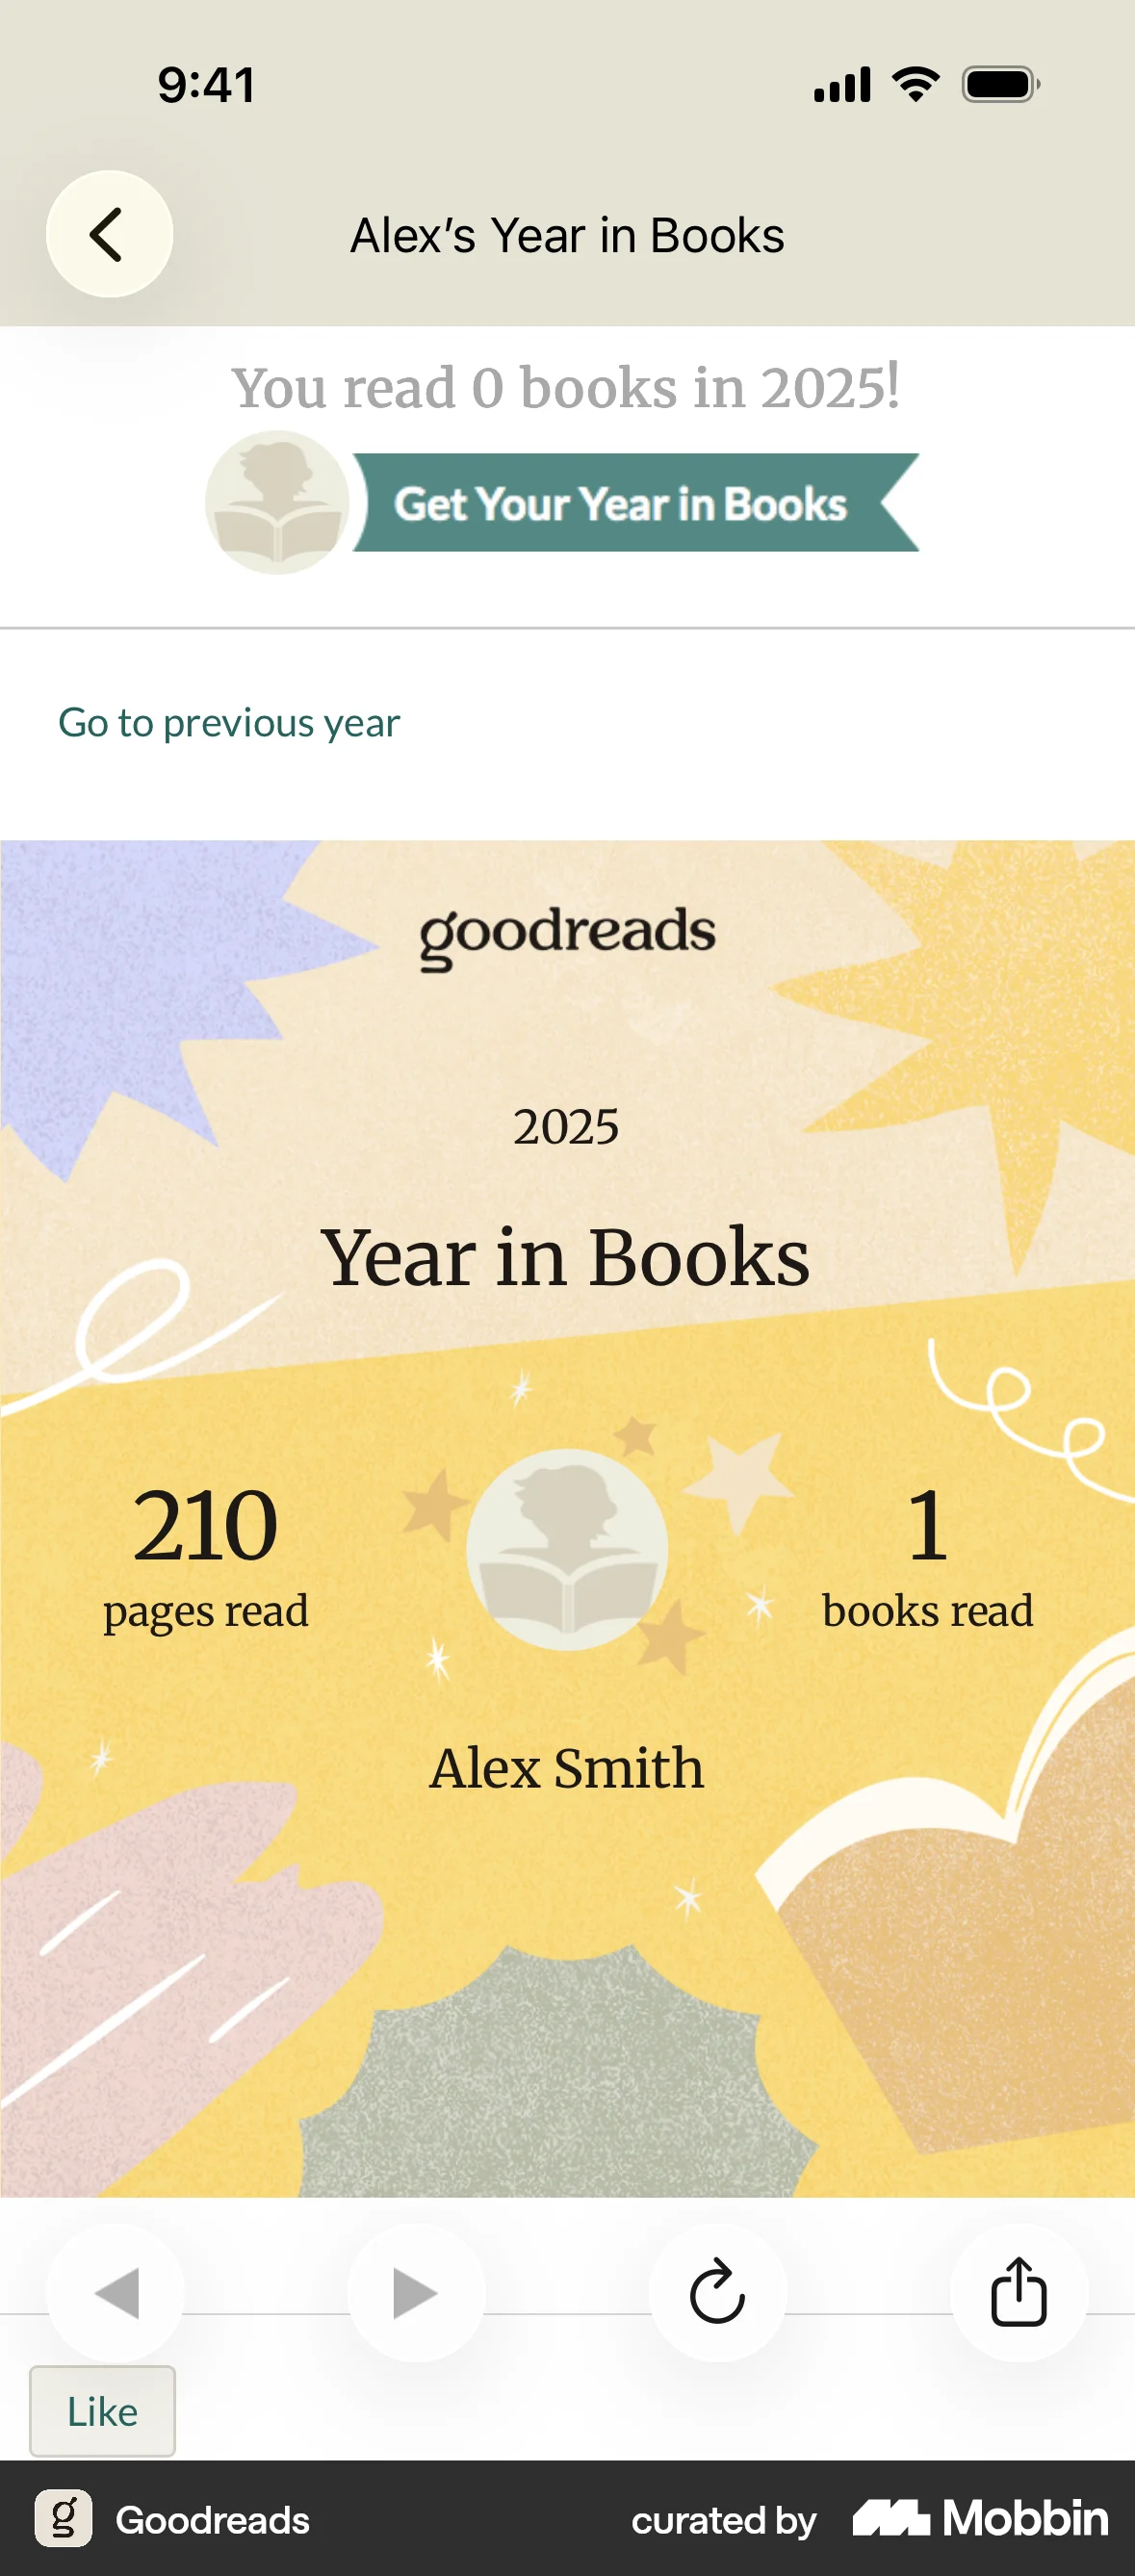
Measuring it
- The metric that shows it worked: continued engagement that survives the removal of the cue. Run the recap or value summary as a holdout and look at retention 60 to 90 days out, not at the session it appeared in. The theatre study's effect was already gone in the window six to nine months after purchase; yours may fade sooner.
- The metric that shows it backfired: cancellation-intent sessions that end without a cancellation and without a subsequent active session. A user who abandoned the cancel flow and then stopped using the product has been trapped, not retained, and will show up later as an involuntary churn, a chargeback or a complaint.
- Secondary backfire signals: time-to-cancel distribution lengthening after a flow change, support tickets containing cancellation language, refund requests, and app-store or review mentions of difficulty cancelling.
- Separate the two mechanisms when you test. One arm shows distance to completion, one arm shows accumulated investment. If only the completion arm moves, you have a goal gradient effect and should stop calling it sunk cost.
References
- Arkes & Blumer (1985). The Psychology of Sunk Cost. Organizational Behavior and Human Decision Processes.
- Sleesman, Conlon, McNamara & Miles (2012). Cleaning Up the Big Muddy: A Meta-Analytic Review of the Determinants of Escalation of Commitment. Academy of Management Journal.
- Ronayne, Sgroi & Tuckwell (2021). Evaluating the Sunk Cost Effect. Journal of Economic Behavior & Organization.
- Ho, Png & Reza (2018). Sunk Cost Fallacy in Driving the World's Costliest Cars. Management Science.
- Pattaratanakun & Mak (2015). Culture Moderates Biases in Search Decisions. Psychological Science.
- Restore Online Shoppers' Confidence Act, 15 U.S.C. § 8403.
- Federal Trade Commission (2024). Negative Option Rule. Final rule, Federal Register.
- Federal Trade Commission (2026). Revision of the Negative Option Rule to Conform to Federal Court Decisions. Final rule, Federal Register.
- Federal Trade Commission (2026). Rule Concerning the Use of Prenotification Negative Option Plans. Advance notice of proposed rulemaking, Federal Register.
- Gibson Dunn (2026). FTC Restarts Negative Option Rulemaking After Eighth Circuit Vacatur; Enforcement Under ROSCA Continues.
- Directive 2011/83/EU on consumer rights, Article 9.
For agents
An agent-friendly guide to this principle lives at /agents/sunk-cost-fallacy.md.
Our MCP server and skills for all principles are coming soon.
Similar principles
Disclaimer: The theories here are just that — theories. They may not apply universally and should be considered in context. Use your own judgment and consult additional sources when applying these principles.